WVOE loans. Your employer verifies your income — no tax returns, W-2s or pay stubs.
With a WVOE loan, your employer completes a written verification of employment, and that form is your income documentation. Built for salaried, hourly and commissioned employees who would rather not hand over tax returns and pay stubs.
- One employer-completed WVOE form is the income file
- No tax returns, W-2s or pay stubs
- Program starts at 660 FICO
- Up to 80% LTV on purchase at 680+ — 75% at 660–679
- Refinance up to 75% LTV at 660+ — cash-out or rate-and-term
- Primary residence or investment property
- Loan amounts from $150,000 · first position only
- Self-employed instead?see the P&L-only loan →
Or skip the form — call or text us: 949-738-9770
What type of property is this?*
What loan type are you interested in?*
What is the property address?*
Depending on location we may have specific programs
What's the purchase price or refinance amount?
Loans from $75,000 up to $5,000,000 — HELOCs from $50,000
Are you purchasing or refinancing?*
How is your credit?*
WVOE starts at 660 FICO
Is the property occupied or vacant?*
When was the property purchased?*
Who are we preparing options for — and where do we send them?*
Legal name of the primary borrower. We'll text and email your scenario — a real person from our Irvine office. Never sold, no spam.
Where should we send your options?*
We'll email your scenario and next steps — never sold, no spam.
Last step — everything look right?*
Review your details and hit Submit — a real person from our Irvine office will reach out. No call centers, never sold, no spam.
Notice: By providing your name and contact information you are expressly consenting to receive communications from Cap Rate Funding, Cap Rate Funding agents, or affiliated partners which may include phone calls (including to any wireless number that you provide) including automatic telephone dialing systems or by artificial/pre-recorded messages, text message and/or emails for the purpose of marketing Mortgage products and services. By providing your information, you understand that your consent is not a condition of the purchase of any product or services, and carrier messaging and data rates may apply. You may revoke this consent at any time by calling us at 949-738-9770 or by emailing us at chase@capratefunding.net to be placed on our do-not-call list. By clicking Submit: I Consent to Receive SMS Notification, Alerts & Occasional Marketing Communication from Cap Rate Funding. Message frequency varies. Message & data rates may apply. Text HELP to 949-738-9770 for assistance. You can reply STOP to unsubscribe at any time.
What's the purchase price?*
Your best estimate is fine — we'll tailor the loan to it
What is the existing balance on your property?*
Include all liens — first, second, HELOC. Enter 0 if it's paid off.
What is the current value of the property? (Your best estimate)*
Your equity sets the maximum loan — this tells us how much room there is.
We can still do this — with a bigger down payment.
For this credit tier, our lenders can approve the purchase only when you bring at least 50% down, plus closing costs, out of pocket. If you can do that, we'll keep going right now — equity does the qualifying that credit can't.
Not sure? Call us: 949-738-9770
You're in! Now lock in your call.
Your scenario is in the queue. Pick a time below and we'll go over your options together — usually the same business day.
To make the call count, have these handy: your property address, a recent mortgage statement (or your payoff balance), and a ballpark of your credit score.
Book My Call — Open CalendarPrefer to talk now? Call 949-738-9770 · Book a call
You're booked! One more thing…
Save our contact now — we'll be calling you from 949-738-9770. With it saved, your phone shows Chase Zhao · Cap Rate Funding instead of “Scam Likely” or an unknown number, so you'll know it's us calling about your appointment.
Prefer to add it yourself? Chase Zhao · 949-738-9770 · chase@capratefunding.net
We can't lend on a primary residence in your state yet.
For a home you live in (or will live in), our lenders are set up in . Your property is in , and we're not able to move forward on an owner-occupied loan there today.
Two honest paths from here: if the property is actually a rental or investment, go back and choose Investment Property — our investor programs cover most states. Otherwise, call or text us and we'll point you to a lender who can help.
Call us to talk it through — 949-738-9770One more question — is your credit score 500 or higher?*
Below 660 the WVOE loan isn't available, but your equity may qualify you for a different program that accepts credit from the 500s.
Good news — your equity opens a better door.
Below 660, the WVOE loan isn't the fit here — but your equity is. Based on your numbers, the Home Equity Agreement can work where a loan can't: cash from your equity with no monthly payments and credit accepted from the 500s — in exchange for a share of your home's future value.
How the HEA worksQuestions? Call us: 949-738-9770
We're not the right fit for this one.
Based on your answers, we aren't able to offer a program for this scenario at your current credit score. WVOE loans start at 660 FICO. If your score improves, we'd love to take another look — and you're always welcome to call us to talk through your options.
Call 949-738-9770We're not licensed to lend on primary residences in your state.
For owner-occupied homes, Cap Rate Funding is licensed in Alabama, Arizona, California, Colorado, Florida, Idaho, Iowa, Louisiana, Maryland, Michigan, Minnesota, New Mexico, Nevada, Ohio, Oklahoma, Oregon, Pennsylvania, Tennessee, Texas, Utah & Washington only. Because this property is your primary residence, we aren't able to help with this one — and we'd rather tell you now than waste your time.
Own an investment property? That's a different footprint — our investor programs are available in nearly every state.
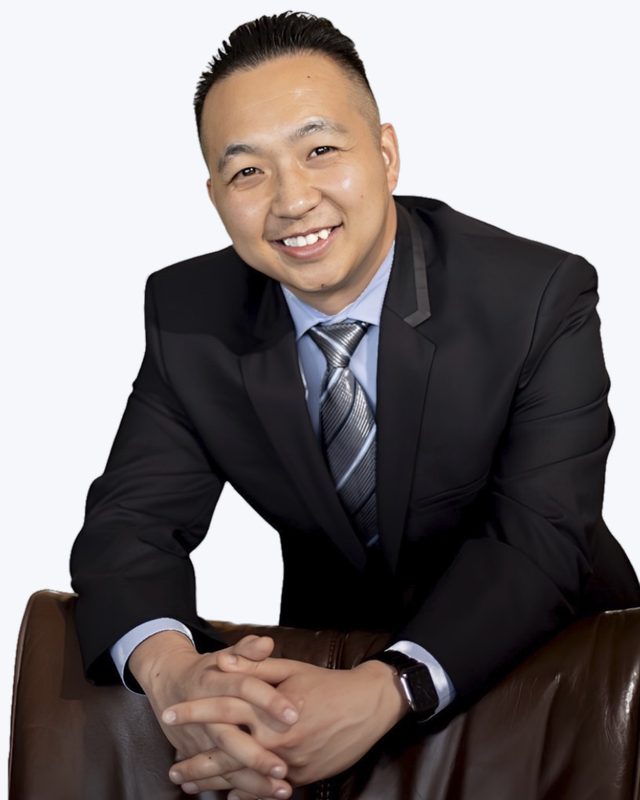 You’ll work directly with Chase Zhao, President · NMLS #1816148
Income is documented by your employer's written verification of employment. Program starts at 660 FICO. Purchase: 20% down at 680+, 25% at 660–679. Refinance (rate-and-term or cash-out): 75% LTV at 660+. Loans from $150,000. First position only — no second mortgage. Subject to program guidelines and credit approval.
Can we fund your deal? Check before you apply.
We'd rather tell you now than waste your time. Here's our lending box, plainly stated.
See exactly what we can & can’t fund
We can help with:
- Financing at 620+ FICO — primary homes and investment properties
- DSCR investment deals at any credit score — LTV is capped by credit tier; below 620 FICO caps at 50% LTV
- Investment property refinances — flexible credit, conditional lending available below 620
- Primary-home refinances under 620 FICO — California properties only
- Free-and-clear cash-out in OR, WA & ID — any credit score, $200,000+, up to 50% LTV
- HEA — credit accepted from the 500s; your FICO band sets the maximum OLTV (60–75%)
- Reverse mortgages — any credit score, primary residence, current balance under 50% of home value
- Loan amounts from $75,000 up to $5,000,000 (DSCR capped at $3M, HEA at $600K)
We're not the right fit for:
- New financing under 620 FICO (except DSCR investment deals, capped at 50% LTV)
- Primary-home refinances under 620 FICO outside California
- Loan amounts under $75,000 ($50,000 for HELOCs)
If your score improves, come back — we'd genuinely love to take another look. Questions about a gray-area scenario? Call 949-738-9770.
Your employer's word is the income file.
One verification form from your employer replaces the tax returns and pay stubs a full-doc loan asks for.
The program in plain numbers.
- Written verification of employment completed by your employer
- 660+ FICO — that's where the program starts
- LTV: purchase 80% at 680+, 75% at 660–679 · refinance 75% at 660+
- Loans from $150,000 · primary or investment · first position only
The paper chase.
- No tax returns — unreimbursed expenses and write-offs don't shrink your income
- No W-2s to dig up
- No pay stubs to collect month after month
- No bank statement reviews to explain
Tailored solutions for every scenario.Three programs fund most deals.
One conversation gets your scenario priced across a network of 100+ lenders — with the trade-offs explained straight.
HELOC, P&L Only, and DSCR do the heavy lifting — one conversation prices your scenario across 100+ lenders. Need something else? Call 949-738-9770.
HELOC
Up to 90% CLTV, funded in as little as 5 days, no appraisal required. $50K–$5M, owner or non-owner occupied, 1–4 units.
Check my equity →P&L Only Loan
Qualify with one P&L — CPA-prepared or self-prepared options, even future income projections. No tax returns, no bank statements. 640+ credit, $150K+.
See P&L options →DSCR
The rent qualifies — not your income. 1–4 unit rental properties, personal name or LLC, no cap on properties. No minimum FICO.
Price my rental →Cash-Out & Investor Refinance
Replace your mortgage and take a lump sum, or reposition rental debt to free up trapped capital.
Compare my options →Rental Property Loans
Financing for 1–4 unit rental properties — including 2–4 unit multi-family.
See rental programs →Hard Money
Asset-based lending for deals that can't wait for a bank. Credit flexible — underwritten on the asset.
Fund my deal →VA Loan
Cash-out up to 100% LTV, plus IRRRL streamline refis with no appraisal, income docs, or minimum FICO. Veteran-first guidance.
See VA options →FHA Loan
Primary residence: 3.5% down at 580+ credit, 500–579 accepted with 10% down. A practical path to your equity.
See FHA options →Reverse Mortgage
Primary residence, any credit score, current balance under 50% of value. Access equity without a monthly mortgage payment.
Check my eligibility →HEA
No monthly payments, up to $600K. Your FICO band sets the max OLTV — 60–75%, all lien positions considered.
Price my scenario →Landlord Insurance
Quote and bind rental-property coverage in minutes through our partner Steadily — so your closing never waits on a policy.
Get an insurance quote →Let the funnel decide.
Answer a few quick questions and we'll route your scenario to the right program — 60 seconds, no hard credit pull.
Find my program →
Non-QM is our specialty.
Cap Rate Funding is a team of non-QM lending experts based in Irvine, CA. When the banks say no, we usually have a yes — DSCR, P&L-only, bank-statement, HELOCs, hard money, and home equity agreements are what we do all day, backed by a network of over 100 wholesale lenders.
When you reach out, your scenario goes straight to our team — no call centers, no hand-offs. We'll tell you quickly whether we can help, what it'll roughly cost, and what we'd need from you. And if a loan doesn't make sense for your situation, we'll tell you that too.
Recently funded deals.
Real closings, straight from our Instagram — HELOCs funded in days, P&L and DSCR loans other lenders passed on.
| Deal Type | Location | Loan Amount | Highlight |
|---|---|---|---|
| HELOC | Santa Fe Springs, CA | $397,000 | Funded in 5 days |
| P&L Loan | Irvine, CA | $930,000 | Primary residence · complex title solved |
| DSCR | Detroit, MI | $1,194,200 | 7-property portfolio, one client |
| Digital HELOC | Rural property · 2+ acres | $276,393 | Funded in 7 days · no tax returns |
| P&L · 2nd Lien | Vale, CO | $400,000 | No full appraisal · rural OK |
| DSCR | New Jersey | $562,500 | Reverse 1031 exchange purchase |
| Cash-Out Refi | Texas (A6) | $350,000 | No income verification |
"Chase truly made the process feel effortless and straightforward. The communication was excellent throughout, and I was impressed by the speed and experience he demonstrated."
Google Review · HELOC client"Chase made our HELOC process incredibly easy, smooth, and fast from start to finish. Excellent communication, professional service, and quick turnaround."
Google Review · HELOC client"Fast, reliable, and very honest. Throughout the loan process, I always knew what the next step was. I truly appreciate the professionalism and support!"
Google Review · Investor clientGo beyond with Cap Rate Funding.
Initial Consultation
Share your scenario — refinance or cash-out — and we'll assess your needs. 60 seconds online or one phone call.
Customized Solutions
Your scenario priced across 100+ lenders, with options tailored to your goals.
Application & Approval
Complete your application and receive fast approvals — often with fewer documents than you'd expect.
Closing & Beyond
Seamlessly close your loan and enjoy continued support on the next one.
Direct lender or broker? With Cap Rate Funding, both.
Cap Rate Funding works as a direct lender and a mortgage broker for WVOE loans. Powered by Federal First Lending LLC (NMLS #2381991), every file is priced against our direct programs and a 100+ wholesale lender network, so you see the best route instead of one lender's box.
Searching for a “WVOE lender” or a “written verification of employment mortgage”? Either way you’ve landed in the right place — one conversation, one point of contact (Chase Zhao, NMLS #1816148), and both routes on the table.
WVOE loan questions, before you ask.
What is a WVOE loan?
A WVOE loan is a non-QM mortgage where your employer's written verification of employment (WVOE) form is the income documentation. You do not provide tax returns, W-2s or pay stubs.
Who fills out the written verification of employment?
Your employer completes and signs the WVOE form confirming your employment and income. We handle the request with you so it goes to the right person.
What credit score and down payment does a WVOE loan require?
The program starts at 660 FICO. Purchases need 20% down at 680+ and 25% at 660-679. Loans start at $150,000.
How much can I cash out with a WVOE loan?
Rate-and-term and cash-out refinances go up to 75% LTV at 660+ credit.
Can I get a second mortgage or HELOC with a WVOE?
No. WVOE is first position only. If you want to keep your current first mortgage, our 5-Day HELOC or a bank statement second lien may fit instead.
Can I use a WVOE loan on a rental property?
Yes. WVOE loans work for a primary residence or an investment property.
WVOE vs. P&L-only loan: what is the difference?
Both use the same LTV tiers, but WVOE starts at 660 FICO while P&L-only starts at 640. WVOE is for employees, documented by the employer's verification form. The P&L-only loan is documented by a single profit and loss statement and fits business owners.
Is Cap Rate Funding a direct lender or a broker for WVOE loans?
Both. Cap Rate Funding, powered by Federal First Lending LLC (NMLS #2381991), works as a direct lender and a mortgage broker, so each WVOE file is priced against our direct programs and a 100+ wholesale lender network.
Will checking my options hurt my credit?
No. Seeing your options uses no hard credit pull.
Fast. Flexible. Funded.
Whether you're tapping equity or repositioning the portfolio — check your options in 60 seconds, with no hard credit pull.